Can Beginners Become Consistently Profitable?
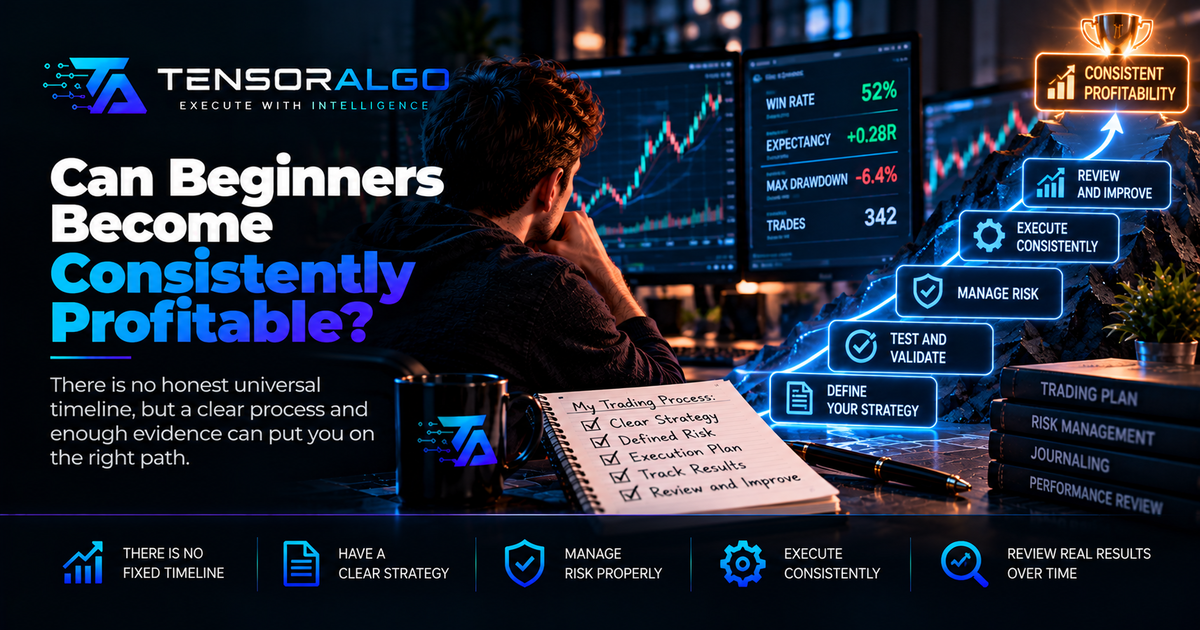
There is no honest universal timeline to consistent profitability. A better question is whether your strategy, risk, execution and review process have produced enough evidence to survive more than one favorable streak.
Beginners often ask one question before almost any other:
How long does it take to become consistently profitable?
The internet is full of confident answers. Three months. Six months. One year. Ten thousand hours. One hundred trades.
There is no verified universal timeline.
Different traders use different markets, strategies, timeframes, account sizes, risk levels and definitions of “profitable.” A trader who takes three setups a week gathers evidence at a different rate from someone who takes ten trades a day. A strategy that works only during one market regime can look consistent for months and then fail when conditions change. A trader can also have positive P&L while taking risks that are too large to survive a normal losing streak.
So the calendar is the wrong measuring tool.
A better question is:
What evidence would show that my process is becoming consistently profitable rather than temporarily lucky?
That is what this guide focuses on. CME Group's Building a Trade Plan provides a useful external framework: objectives, methodology, risk management, trading strategy and a trader log all belong to one working process, and a trading plan cannot guarantee profits.
What Does “Consistently Profitable” Actually Mean?
The phrase sounds simple, but traders often use it to mean completely different things.
It can mean:
- profitable every day;
- profitable every week;
- profitable every month;
- positive expectancy over a large sample;
- able to withdraw money regularly;
- able to pass prop-firm evaluations;
- able to trade full time.
These are not the same thing.
No realistic trading process needs to be profitable every day. Losing trades and losing periods are part of trading.
A more useful definition is:
A consistently profitable process produces positive results over a sufficiently broad sample after realistic costs, while keeping risk within predefined limits and without depending on one unusual winning streak.
That definition is less exciting, but it is measurable.
Why a Few Green Days Prove Almost Nothing
Imagine a beginner has five profitable sessions in a row.
That could be evidence of skill.
It could also be:
- a favorable market regime;
- oversized risk that happened to work;
- one unusually large winner;
- luck across a tiny sample;
- a strategy that has not yet encountered its normal losing sequence.
Now imagine the same trader has fifty trades across several weeks with the same setup, stable risk, realistic costs and consistent execution.
That still does not prove future profitability, but it gives you far more information.
This is why short-term P&L should not be confused with evidence.
The First Milestone: Understand the Instrument
Before profitability, there is basic competence.
For futures traders, that includes understanding:
- contract size;
- tick value;
- point value;
- leverage;
- margin;
- session structure;
- expiration and rollover;
- order types;
- how much one planned stop represents in dollars.
If those mechanics are still unclear, a winning result can be misleading because you may not fully understand the exposure you took.
The CFTC's Futures Market Basics describes speculative futures trading as volatile, complex and risky and advises traders to consider their experience, resources, contract obligations and how much they can afford to lose.
If you are still building this foundation, start with What Is Futures Trading? and the Futures Trading Glossary.
The Second Milestone: One Setup You Can Define Before the Trade
A beginner is not ready to judge profitability if the strategy changes every day.
You need at least one setup that can be described before the outcome is known.
That means you can answer:
- What market condition does this setup require?
- What is the trigger?
- Where is the entry?
- What invalidates the idea?
- How is the target chosen?
- When is there no trade?
- How is position size calculated?
This is the foundation of Rule-Based Trading.
The rules do not have to eliminate all discretion. But they need to be stable enough that the trades belong to the same strategy.
If every loss causes you to redefine the setup, you are not evaluating one strategy. You are evaluating a moving target.
The Third Milestone: Risk Becomes Boring
One of the clearest signs of progress is that position sizing stops being emotional.
The beginner often sizes according to confidence:
- strong setup \= larger size;
- after a loss \= larger size to recover;
- after a win \= larger size because confidence is high;
- near a profit goal \= larger size to finish faster.
A more mature process sizes according to predefined risk.
The Position Sizing Calculator Guide explains the mechanical relationship among entry, stop distance, contract value and position size.
Consistent profitability is difficult to evaluate if risk changes constantly because each trade contributes a different amount of account volatility.
Stable risk makes results easier to interpret.
The Fourth Milestone: You Can Take a Valid Loss Without Changing the Strategy
This is more important than it sounds.
A strategy can be profitable over time and still produce consecutive losses.
The beginner experiences the loss as evidence that something is wrong.
The more experienced process asks:
- Did the setup qualify?
- Was the risk correct?
- Was the trade executed according to plan?
- Is this outcome still within the strategy's tested behavior?
If the answer is yes, the loss may not require any change.
That is a major shift.
You stop treating every individual outcome as a verdict.
The Fifth Milestone: You Have Historical Evidence
Backtesting can help answer basic questions before meaningful money is at risk.
For example:
- How often did the setup appear?
- What was the average win?
- What was the average loss?
- What was the longest losing sequence in the sample?
- How did performance change across market conditions?
- How sensitive were results to costs and execution assumptions?
The Backtesting Guide explains how to structure this work.
Backtesting is not proof of future performance.
A strategy can be overfit. Historical conditions can change. Fills can be unrealistic. Rules can accidentally use information that would not have been available in real time.
The purpose is to eliminate weak ideas and understand expected behavior—not to create certainty.
The Sixth Milestone: You Can Forward-Test the Same Rules
Forward testing is where the strategy meets current market conditions and your real-time decision process.
This is different from looking backward at a chart where every setup is obvious.
During a forward test, you learn whether:
- the setup is recognizable live;
- entries happen too fast for your workflow;
- you hesitate after losses;
- you chase missed entries;
- you change targets under pressure;
- the strategy appears at the expected frequency;
- actual execution costs materially change the result.
The Forward Testing Guide provides a practical framework.
A beginner who can forward-test the same rules for a meaningful sample is already farther along than someone who has spent months switching strategies.
The Seventh Milestone: Strategy Results and Execution Results Are Separated
Suppose your strategy generated twenty valid setups.
You took fifteen.
You skipped three winners because of fear, chased two entries late, moved one stop and exited four winners early.
Your P&L may be negative.
But what exactly failed?
Without separating strategy and execution, you cannot answer.
A proper Trading Journal should record both the planned trade and the actual trade.
Useful fields include:
- setup;
- market condition;
- planned entry;
- actual entry;
- planned stop;
- actual stop;
- planned target;
- actual exit;
- result in R;
- whether every condition qualified;
- whether any rule changed;
- notes on missed or skipped trades.
This allows you to distinguish:
- strategy weakness;
- execution weakness;
- sizing mistakes;
- emotional mistakes;
- data problems.
Without that separation, “I am not profitable” is too vague to solve.
The Eighth Milestone: Costs Are Included
A strategy that makes money before costs and loses money after costs is not consistently profitable in the form you can actually trade.
Costs may include:
- commissions;
- exchange and clearing fees;
- bid-ask spread;
- slippage;
- data/platform costs;
- financing or other product-specific costs where applicable.
Short-term strategies with small average profits are especially sensitive to execution costs.
Do not evaluate a strategy using ideal fills if you cannot obtain those fills in practice.
The Ninth Milestone: Expectancy Matters More Than Win Rate
Beginners often use win rate as the main measure of progress.
That can be misleading.
A strategy can win frequently and still lose money if the losses are much larger than the wins.
A strategy can also lose more often than it wins and remain profitable if winners are sufficiently larger than losers.
The relationship among win rate, average win, average loss and costs is what matters.
Our guide to What Makes a Trading Strategy Profitable? explains this in detail.
Consistency means understanding the distribution, not merely celebrating a high winning percentage.
The Tenth Milestone: You Survive a Losing Streak Without Becoming a Different Trader
This is where many seemingly profitable beginners fail.
The strategy may have positive expectancy, but the trader cannot execute it through normal drawdown.
After three losses:
- size changes;
- setups are skipped;
- new strategies are added;
- stops are widened;
- revenge trades appear.
A process cannot be called consistent if it only exists during winning periods.
Your Risk Management Guide should include maximum trade loss, maximum day loss and rules for handling drawdown.
The objective is not to avoid losing streaks. It is to prevent a losing streak from destroying the method used to evaluate the strategy.
The Eleventh Milestone: Performance Survives More Than One Market Regime
A strategy can look exceptional during one type of market.
For example:
- breakout strategies may thrive during expansion;
- mean-reversion strategies may benefit from balanced conditions;
- trend pullbacks may struggle when price repeatedly reverses;
- very tight stops may perform differently when volatility rises.
If your entire profitable sample occurred during one unusually favorable environment, the evidence is incomplete.
You do not need decades of data before trading. But you should know how dependent the strategy appears to be on the conditions that produced the results.
This is another reason a fixed timeline is misleading. Six months can contain multiple regimes—or one long regime.
The Twelfth Milestone: You Can Define “No Trade” Clearly
A beginner often believes progress means taking more trades.
A mature process knows when there is nothing to do.
If your strategy only works when specific conditions align, then no setup means no trade.
This protects expectancy because it prevents the sample from being polluted by boredom trades and FOMO entries.
The ability to finish a session with zero trades without feeling that the day was wasted is an important step toward consistency.
So How Long Does It Actually Take?
I don't have verified information that supports one universal answer.
Anyone giving every beginner the same timeline is ignoring too many variables.
The time required depends on factors such as:
- how frequently the strategy trades;
- how quickly you can collect a meaningful sample;
- whether you change strategies;
- whether your testing is realistic;
- whether risk is small enough to keep behavior stable;
- how complex the market and setup are;
- how much time you can dedicate to review;
- whether your execution errors are identified and corrected;
- whether the strategy actually has positive expectancy.
A trader can spend three years repeating the same bad habits and learn less than another trader learns in six disciplined months.
Time in the market is not the same as structured practice.
What the Research Can and Cannot Tell Us
Academic work on day traders has found large differences in performance across individuals. In The Cross-Section of Speculator Skill: Evidence from Day Trading, Barber, Lee, Liu and Odean analyze Taiwan day-trading data and find persistent positive ability among a relatively small subset while most traders did not reliably earn positive abnormal returns net of fees.
That is useful evidence that trading ability is heterogeneous.
It is not evidence that a beginner futures trader should expect the same percentages, the same outcomes or a specific timeline. The study concerns a particular historical market, participant group and trading environment.
The correct lesson is narrower:
Some traders demonstrate persistent skill, but skill is not automatic, evenly distributed or created simply by spending time trading.
A Better Question: What Stage Are You In?
Instead of measuring progress by months, use stages.
Stage 1: Mechanics
You understand the product, contract and basic risk.
Stage 2: Strategy definition
You can describe one setup clearly enough to test.
Stage 3: Historical testing
You have evidence about the setup's behavior, including losses and costs.
Stage 4: Forward testing
You can identify and execute the setup in real time without changing its rules.
Stage 5: Small-risk live execution
The dollar risk is small enough that you can follow the process rather than react to P&L.
Stage 6: Process consistency
You follow the same rules through wins and losses.
Stage 7: Positive net sample
Results remain positive after realistic costs over a meaningful group of comparable trades.
Stage 8: Regime resilience
The process has experienced more than one type of market condition without collapsing.
Stage 9: Controlled scaling
Position size increases gradually without changing your behavior or violating risk rules.
This framework is slower than a motivational promise, but it tells you what to work on next.
How Many Trades Do You Need?
There is no single magic number.
Twenty trades may be too few for a noisy strategy. Five hundred trades may still be misleading if the rules changed halfway through.
The sample needs to be:
- large enough to include wins and losses;
- collected under consistent rules;
- representative enough to include realistic variation;
- net of costs;
- free from obvious hindsight bias;
- separated by setup if you trade multiple strategies.
The point is not to reach a round number. It is to reduce the chance that your conclusion depends on a small streak.
How Do You Know You Are Improving Before You Are Profitable?
This is a crucial question because P&L may lag process improvement.
Early progress can appear as:
- fewer impulsive trades;
- smaller average rule violations;
- stable position sizing;
- fewer chased entries;
- fewer moved stops;
- higher percentage of qualified setups taken;
- lower percentage of invalid setups taken;
- more complete journaling;
- smaller difference between planned and actual execution;
- ability to stop after the daily loss limit.
These metrics matter because they show that the process is becoming measurable.
A measurable process can be improved.
A random process cannot.
Should You Trade Live While Learning?
There is no universal rule, but meaningful financial risk should not be required to learn basic mechanics or determine whether a strategy is testable.
Simulation and forward testing can help you collect information without making every mistake expensive.
If you move to live trading, keeping risk small can reveal behavioral differences between simulation and real money while limiting the cost of those lessons.
The goal is to increase risk only after the process earns it.
Should You Quit If You Are Not Profitable After a Year?
A calendar deadline alone is not enough information.
A better diagnosis asks:
- Have you traded one stable strategy or twenty different strategies?
- Do you have a complete journal?
- Is the strategy positive before your execution mistakes?
- Are costs included?
- Does the setup have evidence from backtesting and forward testing?
- Are losses primarily strategy losses or rule violations?
- Has your risk been small enough to preserve capital and decision quality?
If you have a year of disciplined, consistent data showing negative expectancy even with good execution, that is valuable evidence that the strategy needs major revision or replacement.
If you have a year of strategy hopping and undocumented trades, the main problem is that the year did not generate usable evidence.
Consistency Is Not the Same as Income Stability
Even a profitable trading strategy can produce uneven income.
That matters if your long-term goal is to trade full time.
A strategy with positive expectancy may still have:
- losing weeks;
- losing months;
- low-opportunity periods;
- drawdowns;
- changing market conditions.
Do not treat one profitable sample as proof that trading can immediately replace a salary.
Business and personal financial planning require a different level of evidence and capital stability than proving that one strategy has positive expectancy.
How TensorAlgo Fits Into the Learning Curve
TensorAlgo is designed to make a trading process more explicit.
A Playbook can define what market conditions must align, what triggers the setup, where invalidation belongs and how the trade should be monitored.
That can help a beginner move from vague pattern recognition toward something measurable.
If you want to turn your own strategy into a structured workflow, the first Playbook guide explains how to create one.
TensorAlgo does not guarantee profitability and cannot shorten the learning process to a fixed number of days. Its role is to reduce avoidable decision noise and make plan-versus-execution differences easier to identify.
A Practical Profitability Readiness Scorecard
Before calling yourself consistently profitable, ask whether you can answer yes to most of these questions.
Strategy
- Can I define the setup before the trade?
- Do I know when the setup is invalid?
- Have I tested it under consistent rules?
- Do I understand its average win, loss and frequency?
Risk
- Is position size calculated rather than emotional?
- Do I have a maximum trade loss?
- Do I have a maximum daily loss?
- Can I survive a normal losing streak without changing behavior?
Execution
- Do I avoid chasing missed entries?
- Do I keep stops consistent with the plan?
- Do I take qualified setups after losses?
- Do I reject unqualified setups after wins?
Evidence
- Are costs included?
- Is the sample large enough to be meaningful?
- Have I forward-tested the process?
- Have I experienced more than one market environment?
Review
- Do I journal every trade?
- Can I separate strategy losses from execution errors?
- Do I revise rules from evidence rather than frustration?
- Can I explain why performance changed?
If many answers are no, the next goal is not “make more money.”
It is to close those gaps.
FAQ
How long does it take to become consistently profitable in trading?
There is no verified universal timeline. The answer depends on strategy frequency, market, risk, experience, costs, quality of testing and whether the trader follows a stable process. Fixed promises such as three months or one year should be treated cautiously.
Can a beginner become consistently profitable?
It is possible for some traders to develop persistent skill, but profitability is not guaranteed. The more useful objective is to build and test a process with positive expectancy, realistic costs and controlled risk.
How many profitable months prove consistency?
There is no universal number. Several green months can still be driven by one favorable market regime or oversized risk. Evaluate the trade sample, drawdown, costs, execution quality and behavior across changing conditions.
Is win rate the best measure of consistency?
No. Win rate must be considered with average win, average loss, transaction costs, drawdown and trade frequency. A high win rate can still produce negative expectancy.
Should I increase size once I become profitable?
Only gradually, and only if larger dollar swings do not change your execution. Scaling should follow evidence and risk capacity rather than excitement after a profitable streak.
What is the fastest way to improve?
Reduce variables. Trade fewer markets and setups, define the rules clearly, keep risk small, test systematically, journal plan versus execution and review repeated errors. Faster learning comes from better feedback, not necessarily more trades.
Final Takeaway
Beginners can become better traders, and some traders can develop persistent profitable skill. But there is no honest countdown to consistency.
Stop measuring progress only in months.
Measure whether you understand the instrument, trade a defined setup, control risk, test it historically and forward, execute it consistently, include costs, survive losing streaks without changing the rules and produce positive results over a meaningful sample.
Profitability is not a date on the calendar.
It is the point where your evidence becomes stronger than your hope.