How Professional Traders Think
Professional trading is less about certainty than disciplined decisions under uncertainty. Explore probability, base rates, invalidation, risk, process-versus-outcome thinking and review loops that keep one trade from rewriting the whole plan.
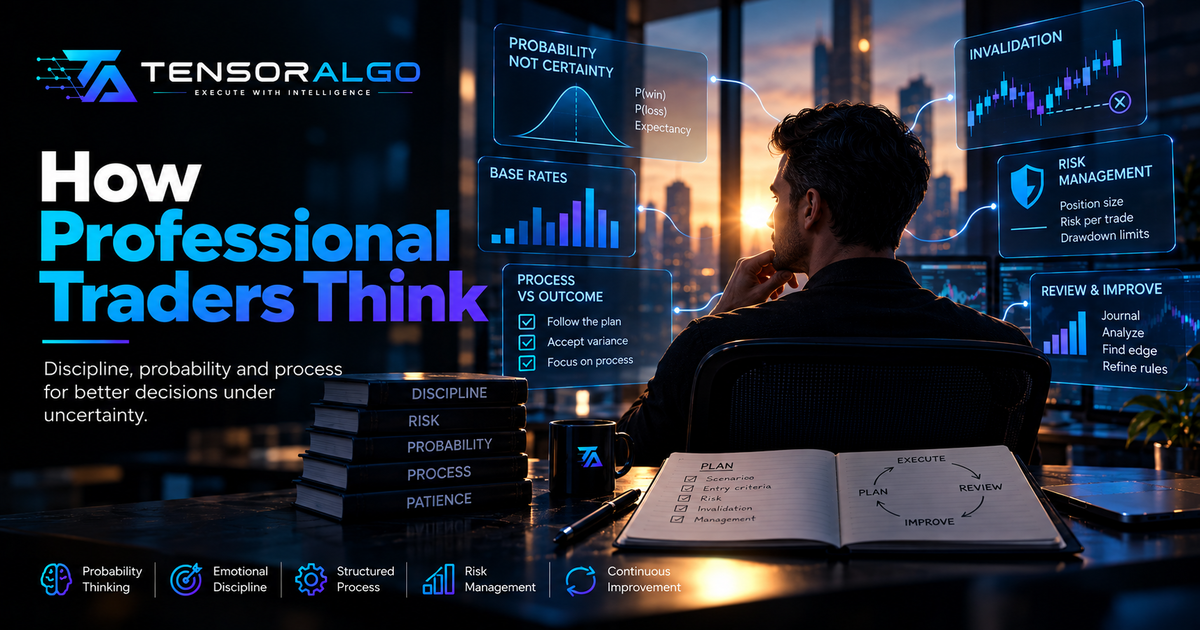
How Professional Traders Think: Probabilities, Risk, and Process
There is no single “professional trader mindset.” Different firms, markets, and strategies operate differently. But durable trading processes tend to share several decision principles: uncertainty is explicit, risk is defined before outcome, and evidence matters more than one trade.
Educational information only. This article describes decision-process principles, not universal traits of every professional trader.
Think in distributions, not certainties
A setup can be valid and lose. A poor decision can make money. Professionals therefore evaluate a series of decisions rather than using one outcome to prove the thesis.
The question becomes “What range of outcomes is plausible under this process?” rather than “Am I right?”
Separate thesis from invalidation
Before entry, define both:
- what evidence supports the trade;
- what evidence would show the premise no longer holds.
A thesis without invalidation can become an excuse to hold indefinitely.
Size uncertainty
Conviction does not eliminate uncertainty. Position size translates uncertainty into a loss the process can tolerate.
Risk is therefore part of the trade definition, not an administrative step added afterward.
Distinguish process from outcome
Four combinations are possible:
- good process / favorable outcome;
- good process / unfavorable outcome;
- poor process / favorable outcome;
- poor process / unfavorable outcome.
The third category is dangerous because profit can reinforce bad behavior.
Avoid outcome bias
After a large move, the correct path can appear obvious. At decision time it was not.
Preserve the information available before entry and review decisions against that evidence rather than the completed chart.
Think conditionally
Instead of a fixed forecast, use scenarios:
- if the level holds and confirmation appears, one playbook is eligible;
- if acceptance occurs through it, that idea is invalid;
- if conditions remain ambiguous, do nothing.
Conditional planning makes changing your mind a feature rather than a failure.
Opportunity cost includes bad trades
Not trading can preserve capital, attention, and risk capacity. A workflow does not need exposure at all times.
The objective is not to participate in every move but to execute the defined opportunity set.
Treat drawdown as information, not identity
A losing period can arise from normal variance, execution mistakes, regime mismatch, or genuine edge degradation.
Diagnose those separately. Increasing risk to recover losses or abandoning rules after a short sample can make the diagnosis harder.
Use checklists where memory is weak
Repeatable tasks—event checks, contract verification, risk calculation, order-state reconciliation—benefit from checklists.
Judgment should be reserved for places where judgment adds value.
Review in batches
Individual trades are emotionally vivid and statistically weak. Scheduled reviews allow patterns to emerge across playbooks, sessions, and regimes.
Define what evidence is sufficient to change a rule before reviewing the latest outcome.
Keep research and execution distinct
During the session, execute the current version. Outside the session, research alternatives. Mixing experimentation into live execution makes performance difficult to interpret.
Technology as cognitive support
Software can calculate, retrieve, alert, reconcile, and summarize. AI can help synthesize evidence. Neither should erase the underlying facts or silently change risk.
Good tools reduce cognitive load while preserving accountability.
There Is No Single Professional Mindset
A market maker, portfolio manager, futures scalper and systematic researcher can have radically different objectives. Avoid mythology. The common ground worth studying is process: explicit risk, uncertainty, evidence, operational discipline and repeatability.
Expected Value Thinking
Expected value does not mean every trade should be calculated with a precise probability. It means judging decisions by their distribution rather than demanding that each individual outcome be favorable. A valid process can lose repeatedly; a bad process can occasionally win.
Base Rates
Before declaring an observation exceptional, ask how often it occurs normally. If a setup wins 55% historically, three losses in a row are not automatically proof that it broke. Base-rate thinking helps distinguish surprising evidence from emotionally vivid but ordinary variance.
Bayesian Updating as a Mental Model
New evidence should change confidence proportionally to its quality. One trade usually deserves a small update; a verified implementation bug deserves a large one. You do not need formal Bayesian equations to use the principle: prior evidence should not disappear because of one new observation.
Pre-Mortems
Before entry or deployment, ask: “If this fails, what are the plausible reasons?” Examples include wrong regime, event shock, stale data, poor fill or rule violation. A pre-mortem exposes risks while action can still be changed.
No-Trade Decisions
A process can correctly produce no action. Opportunity cost is not only missing a winner; taking a low-quality trade consumes risk, attention and sometimes the ability to act on a later valid setup.
Losses as Classified Evidence
Separate compliant strategy losses, execution mistakes, risk violations and operational incidents. Only then can a losing streak inform whether the strategy, trader behavior or infrastructure needs attention.
Decision Journaling
Write the thesis, invalidation and evidence before the outcome. Later compare what was known then with what happened. This reduces hindsight bias and makes discretionary judgment researchable. See the Trading Journal Guide.
Cognitive Bias Research
Behavioral finance research documents biases such as loss aversion and disposition effects. The classic paper by Kahneman and Tversky, Prospect Theory, is foundational context; it does not prescribe a trading strategy.
Professional Risk Resources
The NFA investor resources emphasize understanding leverage, risk and the entities involved in futures markets. Professional process begins with mechanics and risk before strategy narratives.
Technology and Judgment
Use software for calculation, retrieval, monitoring and consistent logging. Use AI for bounded synthesis where useful. Keep the underlying evidence visible so automation reduces cognitive load without becoming an unchallengeable authority.
TensorAlgo as Process Support
TensorAlgo can support a more explicit decision process by organizing user-defined Playbooks, supported market context and trade-review evidence. The value is not certainty; it is preserving what the trader intended, what evidence was available and what happened afterward so decisions can be reviewed consistently. See the Support Center for current scope.
Probability Without False Precision
You rarely need to say a setup has exactly 63.4% probability. Use ranges or qualitative confidence when the evidence cannot support precision. False precision can encourage oversizing.
Risk First
Before asking how much a trade can make, determine invalidation and acceptable loss. This keeps opportunity assessment connected to survivability.
Independent Trades
The next valid setup should be evaluated on its own rules, not as a chance to recover the last loss or protect the last win. Recent P&L is not automatically market information.
Process Goals
Set goals such as complete pre-trade checks, zero unauthorized size changes and consistent journaling. Outcome goals can exist, but they are less directly controllable.
Calibration
Compare confidence at decision time with later outcomes across many cases. If high-confidence trades do not differ from normal ones, confidence may be emotion rather than information.
Contrarianism
Being different from consensus is not automatically an edge. A contrarian trade still needs a hypothesis, evidence, invalidation and favorable economics.
Patience
Waiting is an active decision when the playbook requires conditions that are not present. Measure forced trades separately to see the cost of impatience.
Missed Trades
A missed winner is not necessarily an error. Classify whether the setup was valid and whether the miss resulted from process failure. Avoid changing rules simply to capture the last move.
Review Language
Use factual language: entered before trigger is more actionable than traded badly. Specific descriptions support correction without turning performance review into identity judgment.
Team Environments
Professional desks often separate roles, limits and escalation. Solo traders can borrow the principle by separating strategy research, execution rules and risk limits even when one person performs all roles.
Applying an Uncertainty Budget
Treat attention, capital and operational capacity as scarce. Not every uncertain situation deserves a position. Reserve resources for the opportunity set the playbook was designed to handle.
Not every decision deserves the same confidence. Label what is known, estimated and unknown before acting. If market state is unusual, data quality is degraded or the setup has limited history, reduce the certainty expressed in the plan. That can mean passing, reducing risk within predefined rules, or simply collecting evidence.
This uncertainty budget prevents weak information from being converted into strong conviction. It also improves review: when an outcome surprises you, ask whether the surprise came from normal variance or from an assumption treated as more certain than the evidence justified.
Professional thinking is partly an information-quality discipline. Strong traders do not need an opinion about every movement. They need a repeatable method for recognizing when available evidence is sufficient for their playbook—and when it is not.
Learning Loop
Observation becomes hypothesis, hypothesis becomes test, test becomes evidence, and only then should evidence alter the playbook. This prevents every vivid outcome from becoming a new rule.
Decision Quality Is Different From Outcome Quality
A profitable trade can be a poor decision if it violated the process; a losing trade can be a good decision if it followed a validated plan and remained within risk. Keeping those dimensions separate is essential because markets contain randomness. Otherwise the latest outcome becomes the teacher, even when it carries little information about the quality of the original decision.
A simple review matrix helps:
| | Favorable outcome | Unfavorable outcome | | --- | --- | --- | | Process followed | valid win | valid loss | | Process violated | lucky error | process error |
The bottom-left cell is particularly dangerous: a rule-breaking trade that wins can reinforce behavior that is harmful over a larger sample.
The Trading Psychology article explores behavioral mechanisms behind these reactions, while the Decision Fatigue guide focuses on reducing unnecessary choices before cognitive quality deteriorates.
Think in Conditional Probabilities, Not Certainty
Professional decision-making does not require assigning a precise probability to every setup. It does require recognizing that evidence changes a distribution rather than creating certainty. A playbook may have a positive historical expectancy in one regime and weak evidence in another. The decision is therefore conditional: given this setup, regime, execution environment and risk budget, is the trade eligible?
Base rates matter. If a setup historically appears only a few times in a specific condition, confidence should be lower than for a well-observed state. New evidence can update the working view, but the update should be proportional to its reliability rather than its emotional impact.
The What Makes a Trading Strategy Profitable? guide connects this mindset to expectancy, sample uncertainty and robustness.
Pre-Mortem and Invalidation
Before entry, ask what would make the thesis wrong, what execution failure could occur, and what evidence would justify doing nothing. This “pre-mortem” separates invalidation from discomfort. A stop or cancellation rule should correspond to a reason the planned trade no longer fits—not merely to a desire to avoid realizing a loss.
Risk then converts uncertainty into a bounded decision. The Risk Management Guide and Position Sizing Guide show how planned risk can be separated from conviction.
Review Language Matters
Replace hindsight language such as “I should have known” with factual statements: what information was available, which rule applied, what action was taken, and what happened afterward. That language produces data that can be aggregated. The Trading Journal Guide provides a structure for preserving those decision-time facts.
A professional mindset is therefore not emotional detachment or constant confidence. It is a repeatable way to make, bound and review uncertain decisions without letting one outcome rewrite the process.
A Repeatable Decision Review
After the session, choose several decisions—not only the largest wins or losses—and reconstruct them in order. What was known before the trade? Which playbook was eligible? What would have invalidated it? How much risk was available? Which new information appeared after entry? This sequence prevents later information from contaminating the review.
Then classify each observation as process evidence, market outcome, or new hypothesis. Process evidence can justify fixing an execution mistake immediately. A market outcome usually belongs in the sample. A new hypothesis belongs in research, not in tomorrow's rules.
Professional thinking also includes knowing when evidence is insufficient. If a setup has a tiny sample, a new regime has appeared, or the data source is questionable, reducing confidence is more rational than inventing precision. The ability to say “unknown” protects the research process from forced narratives.
Finally, review whether attention was allocated well. Did the trader spend most cognitive effort on decisions that could change risk, or on commentary that had no actionable consequence? This is where workflow design and mindset meet: better defaults, alerts and playbooks preserve judgment for the few decisions that genuinely need it.
A useful weekly question is not “Was I right?” but “Which decisions were repeatable, which assumptions were unsupported, and what evidence would change the process?” That framing keeps learning tied to observable behavior rather than confidence or regret.
Final Practice
Before the next session, write one sentence for the base case, one for the main invalidation and one for the maximum risk you are willing to accept. After the session, score the decision using only information that existed at the time. Repeating that exercise trains calibration more effectively than judging yourself from the final chart.
Calibration Over Confidence
Track whether your confidence categories correspond to different observed outcomes over time. If high-confidence and ordinary setups behave the same, the confidence label may not contain useful information. Calibration turns subjective conviction into something reviewable and discourages increasing risk simply because a trade feels unusually compelling.
Frequently Asked Questions
What does “thinking like a professional trader” mean?
It means treating decisions as conditional and probabilistic, defining invalidation and risk before the outcome, and reviewing process quality separately from short-term P&L.
Why separate decision quality from outcome quality?
A good process can produce a losing trade and a poor process can produce a winner. Conflating the two encourages hindsight bias and unstable rule changes.
How should uncertainty affect a trade?
Uncertainty should change confidence, risk or the decision to participate according to predefined rules rather than being hidden behind false precision.
Do professional traders need to predict every market move?
No. A robust process can include no-trade decisions and focus only on situations that match the trader's defined opportunity set.
Final Takeaway
Professional decision-making is less about certainty than disciplined updating. Define the thesis, invalidation and risk before the outcome; distinguish process from P&L; and let repeated evidence—not one vivid trade—change the playbook.