Your Strategy Isn't the Problem - Your Execution Is
A trading strategy and the trades you actually execute are not the same dataset. Learn to diagnose late entries, missed setups, risk deviations, and weak signals without confusing discipline with profitability.
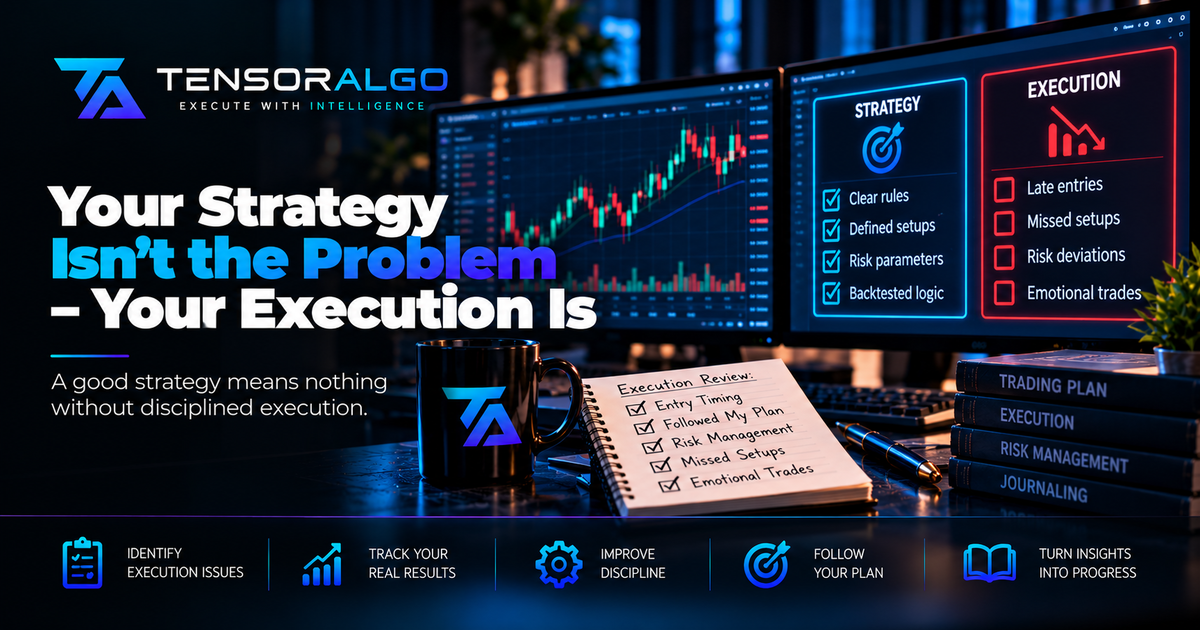
Your Strategy Isn't the Problem—Your Execution Is
You have spent months learning market structure. You know what a liquidity sweep looks like, how VWAP can provide context, and where an order block might sit. Your charts are organized. Your strategy sounds convincing when you explain it to a friend.
Then the session starts. You take an early entry because the candle is moving quickly. You miss the exact trigger when you look away. You take a second trade that does not fully qualify because the first one lost. At the end of the week, your journal shows an unhelpful mixture of planned and improvised decisions.
The first question is not whether you need a new strategy. It is whether you have tested the strategy you say you trade.
The title of this article is deliberately provocative. Execution is not always the problem. A clearly executed strategy may genuinely lose money after fees and slippage. But many developing traders cannot distinguish a poor signal from an inconsistent implementation. The solution is to separate the two problems and collect useful evidence before making changes.
Three Different Things That Traders Call a Strategy
A trading idea is a recurring observation such as "price often retests the prior day's value area before continuing." An eligible setup is a written combination of market context, trigger, invalidation, time restrictions, and risk parameters. A trade is what actually happened when you attempted to act on that setup.
These are different datasets. Ideas can be plausible without becoming testable rules. Setup candidates can qualify without producing a fill. Executed trades may deviate from the original plan because of spread, slippage, hesitation, order rejection, or a change in the trader's judgment.
If your journal records only fills, it misses missed setups and opportunities correctly rejected because the signal was incomplete. If you assess every fill as a valid expression of the original idea, it mixes execution error with the underlying signal.
The Rule-Based Trading guide explains why trading conditions need to be explicit rather than reconstructed after price has already moved.
The "Perfect Setup" That You Never Actually Took
Imagine a hypothetical NQ pullback setup. Your rules call for a directional context, a retest of a defined level, a confirmation candle, a stop beyond invalidation, and a minimum distance to the next target. The confirmation appears, but you are checking another chart. You notice the move three candles later and enter anyway.
Later, price hits the original target. You write "winning strategy" next to a trade that may have had very different entry risk/reward and stop placement than the signal you intended to study.
Or price reverses and you write "strategy failed," even though the trade entered well beyond the valid zone. In both cases you are evaluating a late chase, not the documented pullback.
The corrective action is to record the decision time, original qualifying entry zone, expiry condition, and actual order. Your Trading Journal should preserve the difference between planned and executed trades.
Why More Indicators Won't Repair a Broken Workflow
When trades do not go well, adding another confluence filter can feel scientific. Perhaps you require VWAP, three moving averages, two candle patterns, and a new momentum signal. But ask what each extra signal changes.
If your actual failure is entering before the first valid trigger, more filters may only increase hesitation or create conflicting evidence. If you repeatedly overtrade after a stop-loss, even a perfect trend filter will not prevent a trade you know is invalid. If you miss setups because you are away from the screen, adding indicators does not improve attention.
Filters deserve a role only when there is data showing they distinguish better opportunities under a stable testing process. Your first repair may be a short checklist, alert monitoring, fixed position-sizing calculation, or more complete recording rather than a new prediction model.
Diagnose the Strategy and Execution Separately
A clean analysis compares two populations. The first is every qualified setup identified from contemporaneous data under fixed rules. The second is every actual trade associated with those setups plus any unplanned trades.
For each qualified setup, record whether the trigger occurred, whether there was a fill, intended entry and invalidation, and the reason it was not taken. For each fill, record actual entry, size, exit, fees, slippage assumptions where necessary, and deviations.
Then ask two separate questions: Did the signal population demonstrate positive net expectancy under realistic executable assumptions? And how much did live implementation change the risk and outcome distribution?
The first question requires careful historical and forward evidence, not just hindsight charts. The second requires an honest event log. Combining them prematurely makes it tempting to optimize a trading signal that may not be the main source of the problem.
Measure the Cost of Early Entries
An early entry is not automatically a bad trade; some strategies intentionally anticipate a trigger. The problem arises when your strategy requires confirmation and you enter before confirmation without defining that as a separate experimental variant.
An anticipated entry might have a better price but a lower qualifying standard. A confirmed entry may happen farther from invalidation. Each needs its own entry definition, stop policy and sample. Switching opportunistically between them means you no longer know which decision rule generated your results.
During review, label "pre-trigger" entries explicitly. Identify the information available at that moment. If you wish to test them, create a new strategy variant with a version number instead of rewriting the current strategy after an attractive winner.
This protects analysis from treating lucky deviations as evidence that the rules were wrong.
Measure the Cost of Late Entries
Late entries create a different problem. When price moves away from the planned zone, the original stop may now be farther away, and less room may remain to the target.
Consider a purely illustrative long with intended entry 100, invalidation 98, and target 104. The intended gross reward-to-risk is 4/2, or 2R. If the trader enters at 102 while retaining the same invalidation and target, the remaining reward is 2 against risk of 4, or 0.5R before costs. These are hypothetical prices, not market levels or performance observations.
Chasing did not change the chart thesis, but it materially changed the trade economics. A position-sizing calculation alone will not recover a favorable entry location.
Set an explicit maximum entry deviation or minimum remaining reward-to-risk. If the trade no longer fits, accepting a missed setup can be a correct strategy decision.
Separate Planned Risk From Actual Risk
Suppose your risk budget is fixed in dollars, but you frequently widen stops after entry. The original risk calculation no longer describes the amount of exposure you chose to accept.
Likewise, two positions in correlated instruments can concentrate risk even when each appears acceptable in isolation. A single stop-loss order does not replace daily loss caps or portfolio exposure checks.
CME's trade-plan risk lesson recommends defining leverage, trade limits, day limits and exposure. Futures prices can gap, slippage can occur, and stops are not guaranteed to fill at the stated price.
Track the planned stop, actual changed stop, quantity, realized costs and maximum exposure. The Risk Management Guide offers a larger framework.
Why a Winning Rule Violation Still Matters
One of the most difficult habits is celebrating a noncompliant win and condemning a compliant loss. This trains the process around recent outcomes rather than around the quality of the decision.
Suppose you took a setup without required confirmation and happened to exit profitably. That is a good financial outcome from a decision outside the strategy's rules. If you silently add the trade to your qualifying setup sample, your results become less interpretable.
Conversely, a properly identified setup may lose. That outcome should count in a clean strategy sample. You may later learn that the strategy lacks edge; but one losing trade does not prove the decision process was inconsistent.
Maintain two fields: outcome and compliance. Both matter. Neither can substitute for the other.
FOMO Is an Information-Processing Problem Too
Fear of missing out is often discussed purely as emotion. In practice it can also be a poorly designed decision workflow. If your rules do not say when an entry expires, every movement away from the zone demands a new judgment under pressure.
Define the order of checks before the session: context first, trigger second, risk and available room third, then entry permission. Add a clear "expired" condition. A missed move then has a defined category rather than a vague feeling that the market owes you another chance.
If you cannot watch all relevant charts, reduce the number of markets or use an appropriately configured monitoring tool. Do not simply trade faster to compensate for an attention bottleneck.
The goal is not to remove human judgment completely. It is to eliminate unnecessary repeated decisions that should have been answered by the plan.
Missed Setups Are Not All the Same
A journal entry marked "missed" is not enough to diagnose the problem. Was the trader offline, distracted, waiting for more confirmation than the rules required, blocked by daily risk limits, or unable to receive market data?
Each cause needs a different response. A valid risk-limit rejection is not an execution failure. A delayed alert may be an operational issue. A skipped entry after a losing streak may be a behavioral consistency issue. A setup noticed only with hindsight may not have been practically detectable at all.
Capture the original signal's timestamp, available information, planned market conditions, and reason for nonparticipation. Review only with information that really existed at that time.
The Forward Testing Guide is relevant because it treats live recognition as part of validating a system—not something automatically solved by a historical chart.
A Five-Question Pre-Trade Gate
A short gate can keep common mistakes from entering the trade sample:
- Did the exact strategy version's conditions qualify?
- Is the entry still inside the defined timing and price window?
- Is the invalidation specific and the quantity within risk limits?
- Is there sufficient realistic room to the target after costs?
- Are data, connection, and order state reliable enough to act?
These questions are not universal strategy recommendations. Adapt the gate to the actual method and instrument. The point is to identify checks that should not vary because a previous trade won or lost.
If a mandatory check fails, record "no trade" with the failed condition. A useful system includes explicit reasons for abstaining.
The Difference Between a Trade Log and an Execution Audit
A simple trade log may show a date, symbol, entry, exit and P&L. An execution audit answers why the trade was or was not permitted in the first place.
For each candidate, capture strategy version, session context, qualifying conditions, data timestamp, direction, planned entry and invalidation, planned size, opportunity expiration, and outcome of the decision gate.
For executed trades, add broker-reported fills where available, actual size and fees, discretionary overrides, final exit and realized result. Distinguish a quote touching a level from a confirmed execution. If records are uncertain, label them uncertain instead of inventing fills.
This makes later comparisons more reliable and exposes problems that a net P&L line cannot explain.
Backtests Do Not Prove Execution Quality
A historical test can estimate a strategy's behavior under specified rules and execution assumptions. It cannot automatically reconstruct the frustration of missing a real-time move, real order delays, or your capacity to follow the strategy through losses.
The National Futures Association explicitly notes limitations in hypothetical performance results, including hindsight, market liquidity, slippage, and the ability to adhere to a program under financial risk.
This does not make backtesting useless. It means historical evidence answers a narrower question than live execution testing. If backtesting shows weak net expectancy even under reasonable assumptions, polishing your discipline alone is unlikely to create a robust edge.
If backtesting appears attractive, forward testing helps reveal what the real workflow can and cannot reproduce.
A Weekly Diagnosis You Can Actually Use
At the end of a week, split your records into valid qualified setups, compliant fills, noncompliant fills, valid skips due to risk rules, accidental missed setups, and incomplete observations.
Calculate how many opportunities were identified in real time, how many were handled according to rules, and the frequency and type of each deviation. Then inspect strategy outcomes under a clearly described fill model, with costs.
Do not treat a single week as proof of statistical edge. Use it to identify operational issues, not to declare victory or abandon the strategy. If no high-quality setups appeared, a week of zero trades may show successful adherence to the plan.
The objective is to make the next improvement specific: reduce late entries, improve alert coverage, enforce fixed quantity, or fix unreliable timestamp records.
When the Strategy Really Is the Problem
There are cases where execution is excellent and the method is still weak. Perhaps your setup appears only in rare conditions. Perhaps its average target is too close relative to the spread and fees. Perhaps positive results disappear when the entry assumption is shifted by one realistic tick or when the market regime changes.
If a meaningful collection of consistent, net-costed observations remains poor, investigate the actual signal. Do not blame yourself or add generic psychological routines as if mindset can reverse negative mathematical expectancy.
Version changes should have a clear hypothesis, a separate test set where possible, and acceptance criteria defined before looking at outcomes. Improvement means isolating one decision variable rather than changing entries, exits, filters and sizing all at once.
See What Makes a Trading Strategy Profitable? for the relationship between win rate, payoff size and trading costs.
How AI Assistance Fits In
AI-assisted software can help organize market observations, monitor specified conditions, and draw attention to potential trades. A structured Playbook can keep eligibility and planned risk visible. Those functions may reduce manual tracking burden.
But AI assistance cannot make a weak strategy profitable by definition, and no assistant can guarantee that an alert arrives in time, market data is fresh, or the trader will act correctly. Model-generated explanations and summaries should be checked against reliable event records.
TensorAlgo helps users turn defined rules into monitored Playbooks and review supported trade activity. To build your own Playbook, use the first Playbook guide. That workflow is different from browsing the public marketplace, where users discover or access other creators' Playbooks.
Keep final execution controls and financial risk boundaries explicit regardless of how much market monitoring you delegate.
A Two-Week Execution Reset
Choose one named strategy version and freeze its entry, risk and no-trade criteria for the experiment unless a safety defect requires suspension. Keep risk appropriately limited and use simulation where appropriate.
Before each session, confirm instruments, contracts, economic events, data health and risk boundaries. During the session, record every valid candidate, including those missed or deliberately rejected. After the session, reconcile fills and costs and classify compliance independently from result.
At the end of the period, write a one-page diagnosis: which deviations occurred, how often they occurred, and what single process adjustment could make the next test cleaner. Two weeks is a workflow experiment, not proof of future returns. Continue collecting data rather than manufacturing a conclusion from a short streak.
Frequently Asked Questions
Should I stop looking for new strategies?
Not necessarily. Research is useful. Separate research from live rule changes so the current method generates interpretable evidence.
Is a high rule-adherence rate proof of profitability?
No. A strategy can be consistently executed and still lose after costs. Adherence is a process metric, not an edge metric.
Can alerts eliminate missed setups?
Alerts can improve visibility, but feed delays, configuration, timing and user attention can still create misses. Measure the complete notification-to-decision workflow.
Should I include a trade that broke my rules?
Record it honestly, but classify it separately from the strategy's compliant setup population. Never erase a losing deviation or count a lucky one as validation of the documented signal.
How should I interpret a losing week with perfect execution?
Check the sample and prevailing market conditions. A short loss sequence may be within expected variation; persistent negative net results across a suitable sample warrant strategy review.
Final Takeaway
Do not assume you need a new strategy merely because your results are inconsistent. First establish whether you are actually trading the same defined system from one session to the next.
Capture qualified opportunities, actual fills, skipped setups, costs and deviations separately. Fix measurable workflow errors, then judge the strategy from a stable sample. The result may be improved discipline, a rejected strategy hypothesis, or both. Either outcome gives you clearer evidence than another month of strategy hopping.